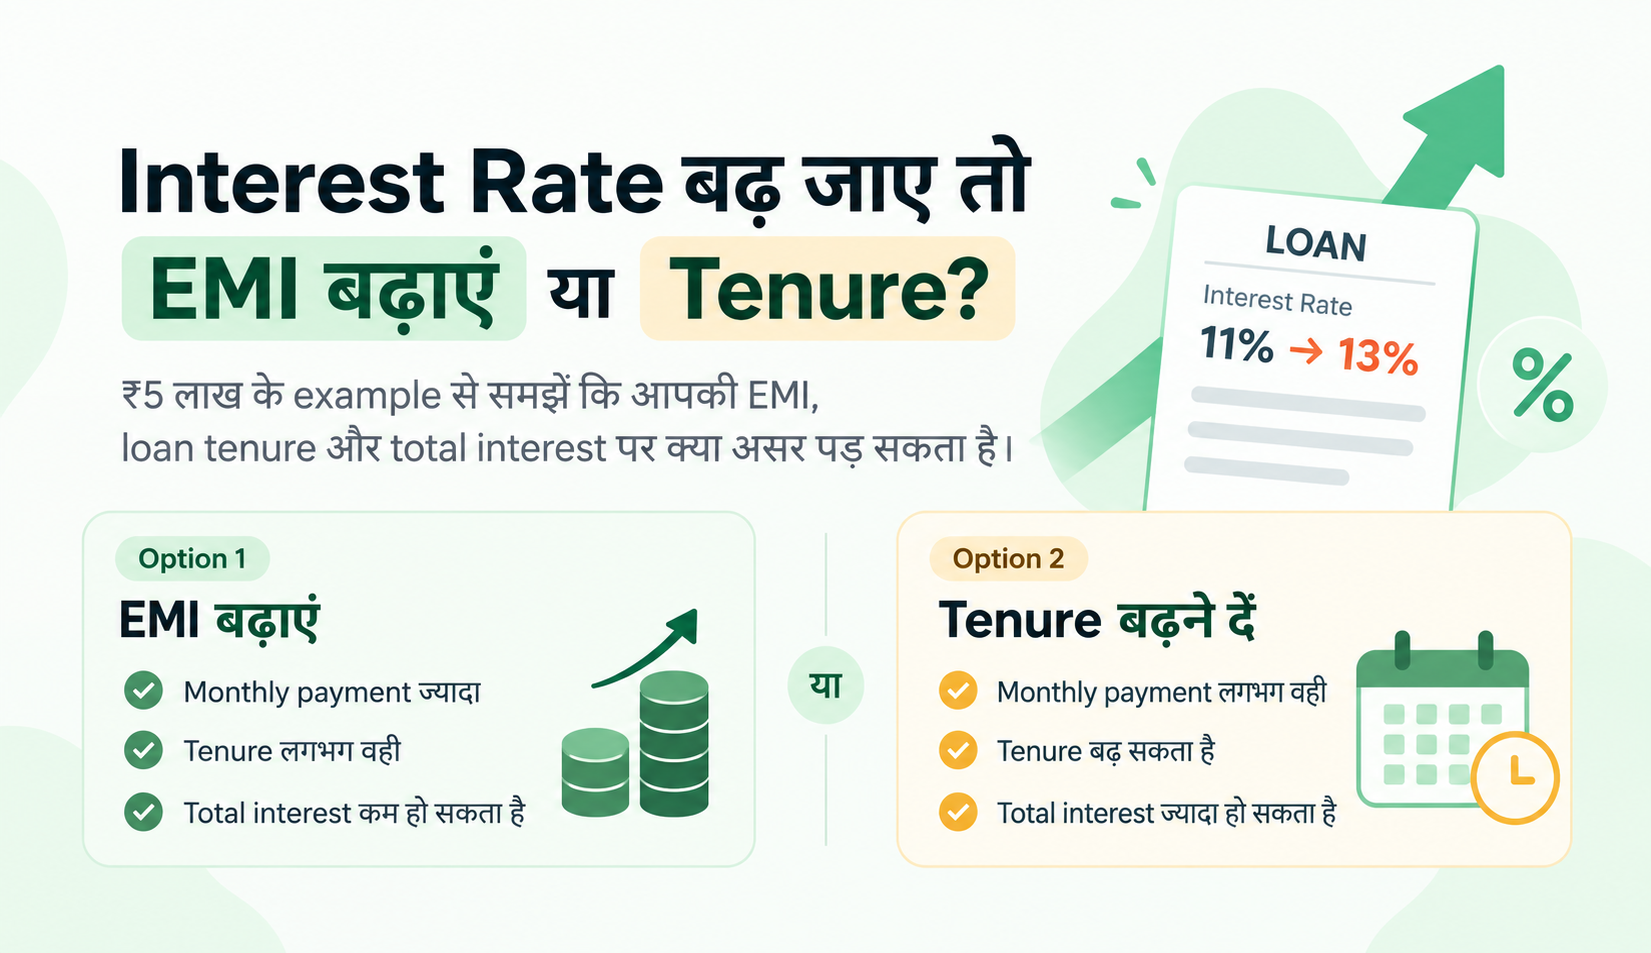
Interest Rate बढ़ जाए तो EMI बढ़ाएं या Tenure? Loan पर असली असर समझें
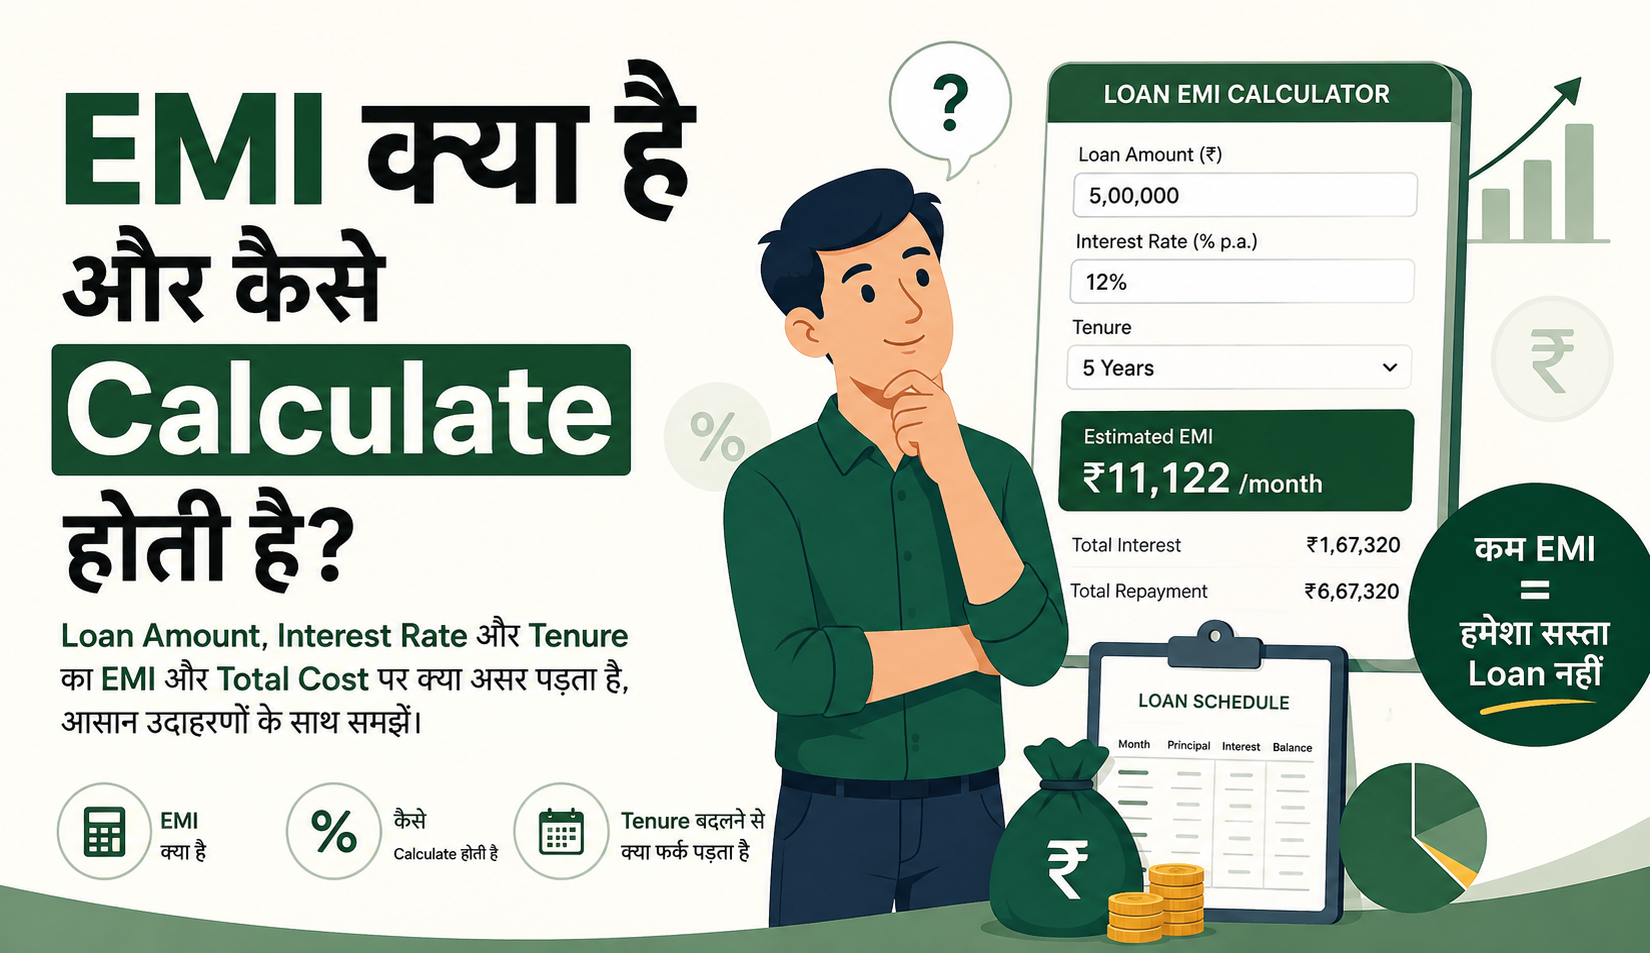
Loan की interest rate बढ़ने पर EMI बढ़ सकती है या tenure लंबा हो सकता है। ₹5 लाख के example से EMI Same vs Tenure Same का असर और total interest का फर्क समझें।
Learn. Plan. Grow.
Practical articles, guides और tools for every stage of your financial journey — बिना unnecessary jargon के.
अपने current financial goal से शुरुआत करें.
Guided learning paths that connect guides, videos, and calculators.
एक important financial question, deeply explained.

Loan की interest rate बढ़ने पर EMI बढ़ सकती है या tenure लंबा हो सकता है। ₹5 लाख के example से EMI Same vs Tenure Same का असर और total interest का फर्क समझें।
Topic चुनें और relevant content तक जल्दी पहुंचें.
Practical, problem-solving financial education.

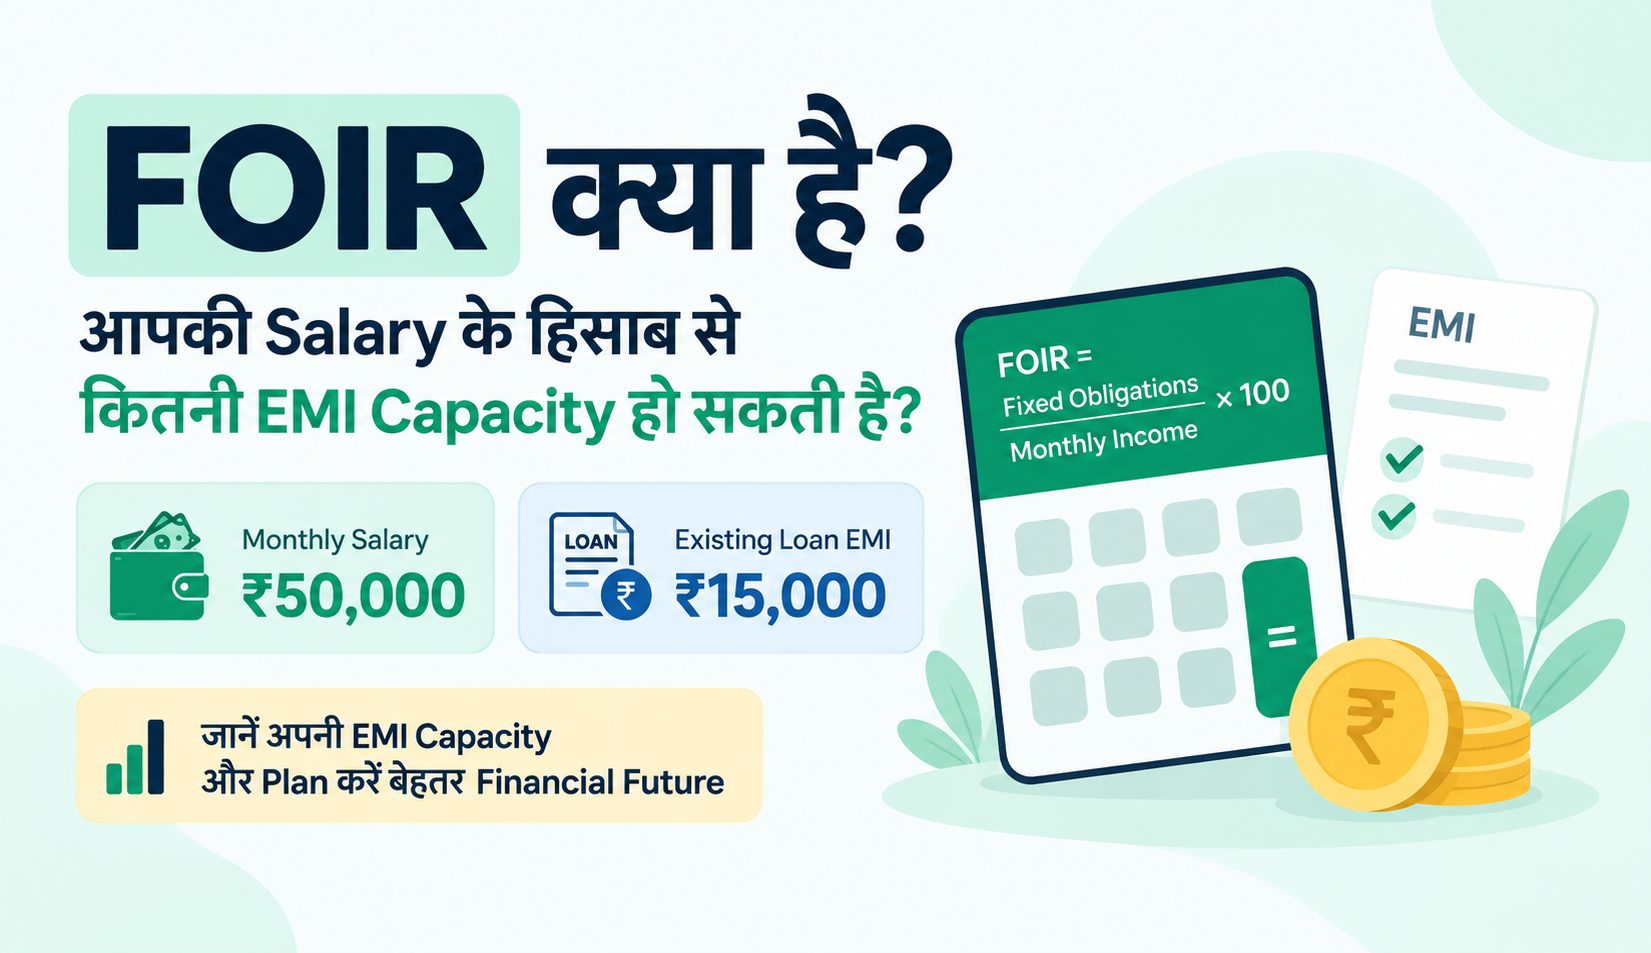
FOIR क्या है और आपकी income का कितना हिस्सा existing EMIs में जा रहा है? ₹50,000 salary और ₹15,000 EMI के example से FOIR और additional EMI capacity आसान तरीके से समझें।

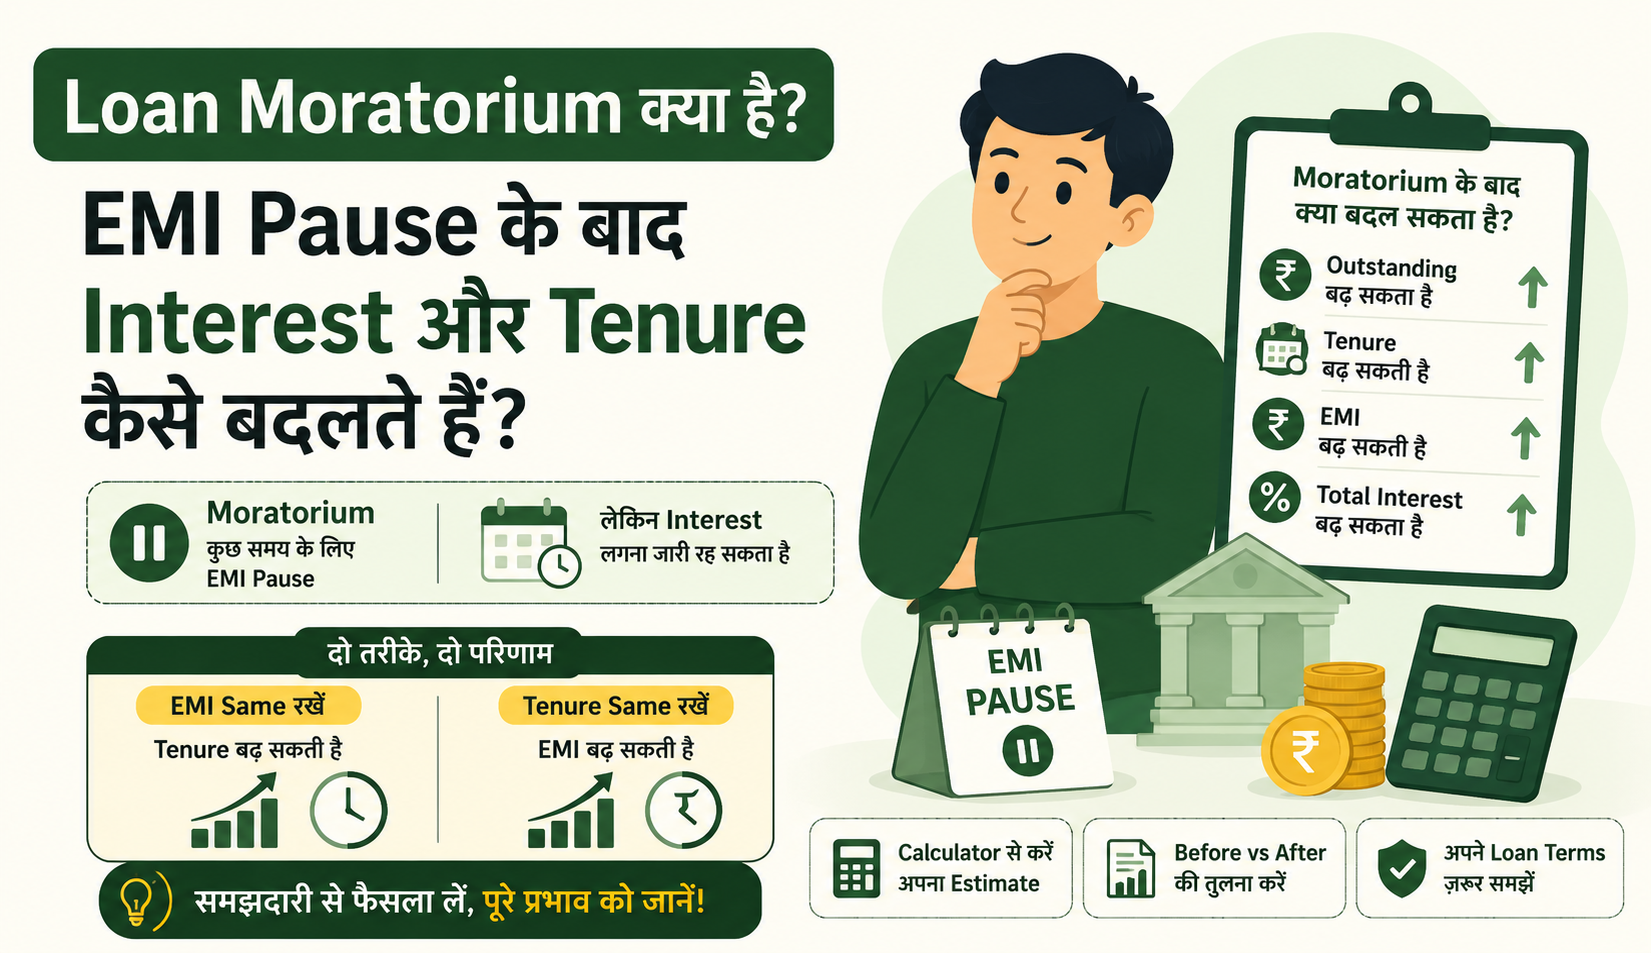
Loan Moratorium में EMI कुछ समय के लिए pause हो सकती है, लेकिन interest जरूरी नहीं कि रुक जाए। समझें Moratorium के बाद Outstanding, EMI, Tenure और Total Interest कैसे बदल सकते हैं।

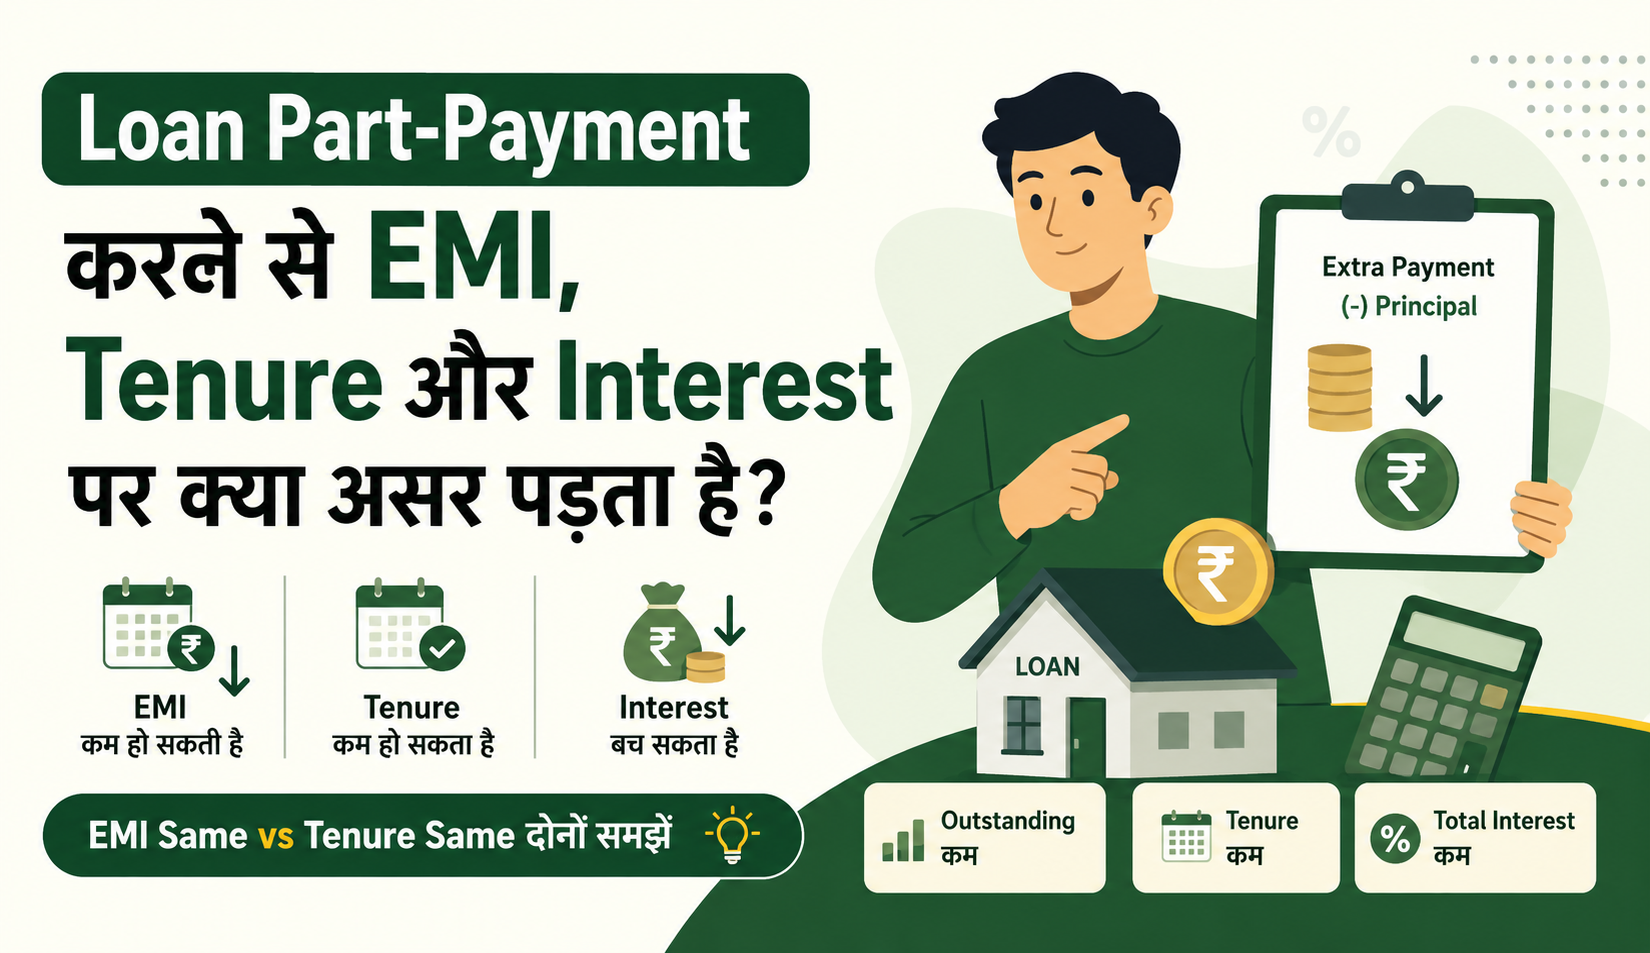
Loan Part-Payment करने से EMI कम होगी या Loan जल्दी खत्म होगा? आसान examples से समझें कि extra payment आपके Outstanding Principal, Tenure और Total Interest को कैसे बदल सकती है।

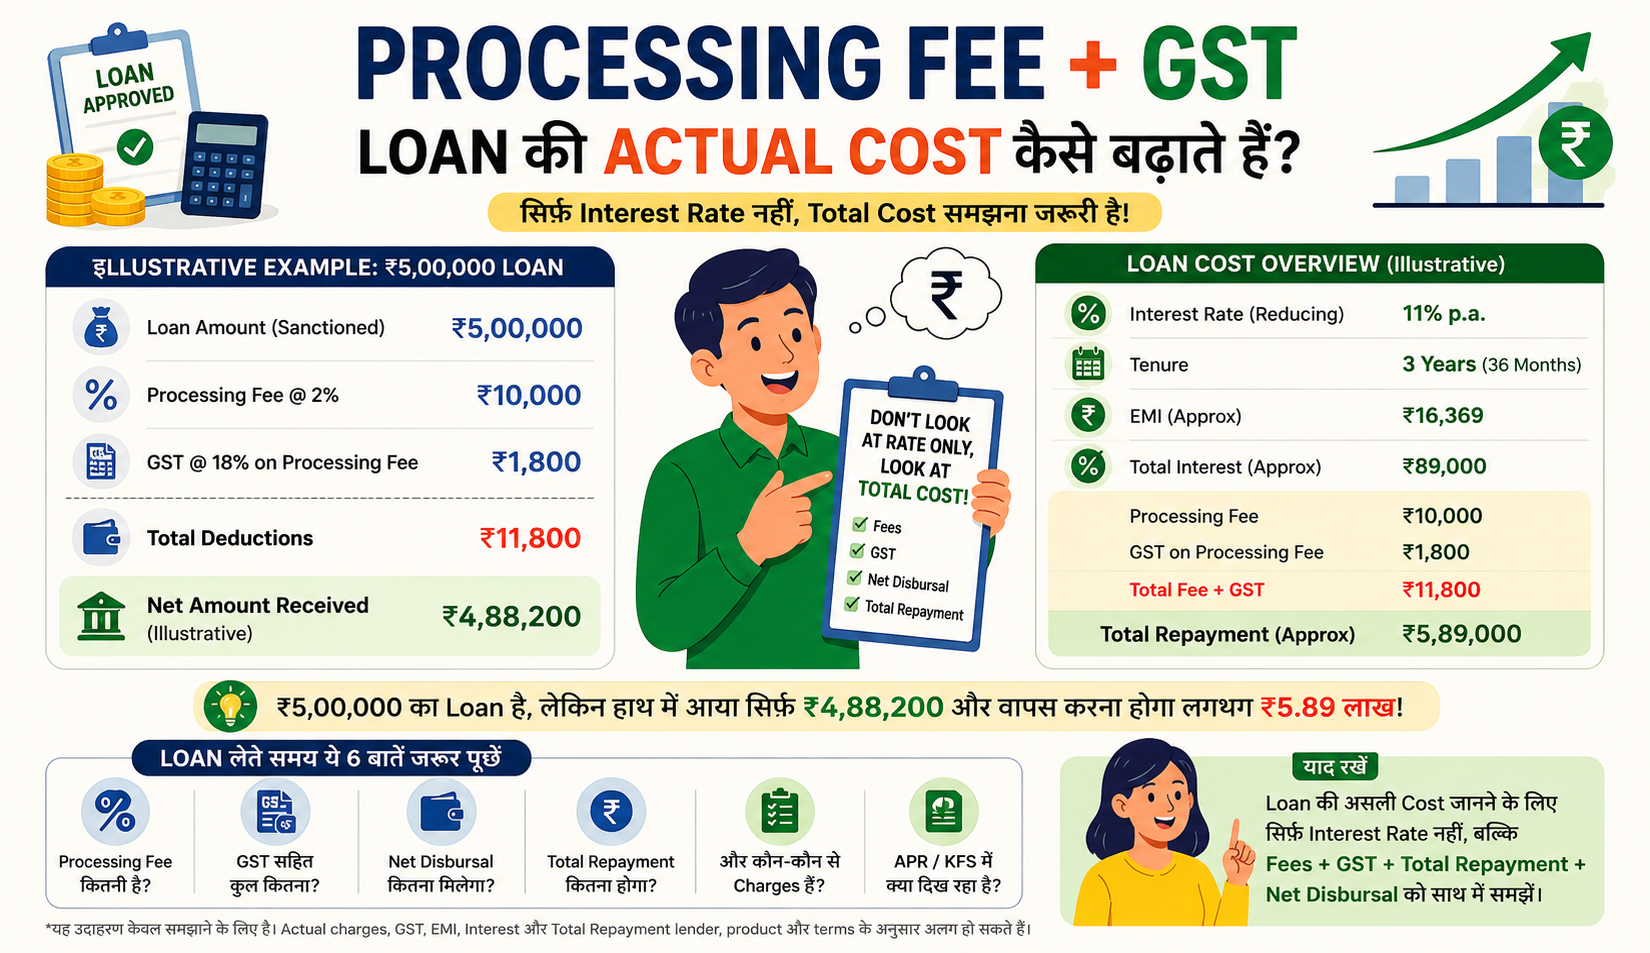
Loan पर सिर्फ Interest और EMI देखना काफी नहीं है। Processing Fee + GST आपके हाथ में मिलने वाले Net Disbursal को कम और overall borrowing cost को बढ़ा सकते हैं। आसान ₹5 लाख example से समझें।

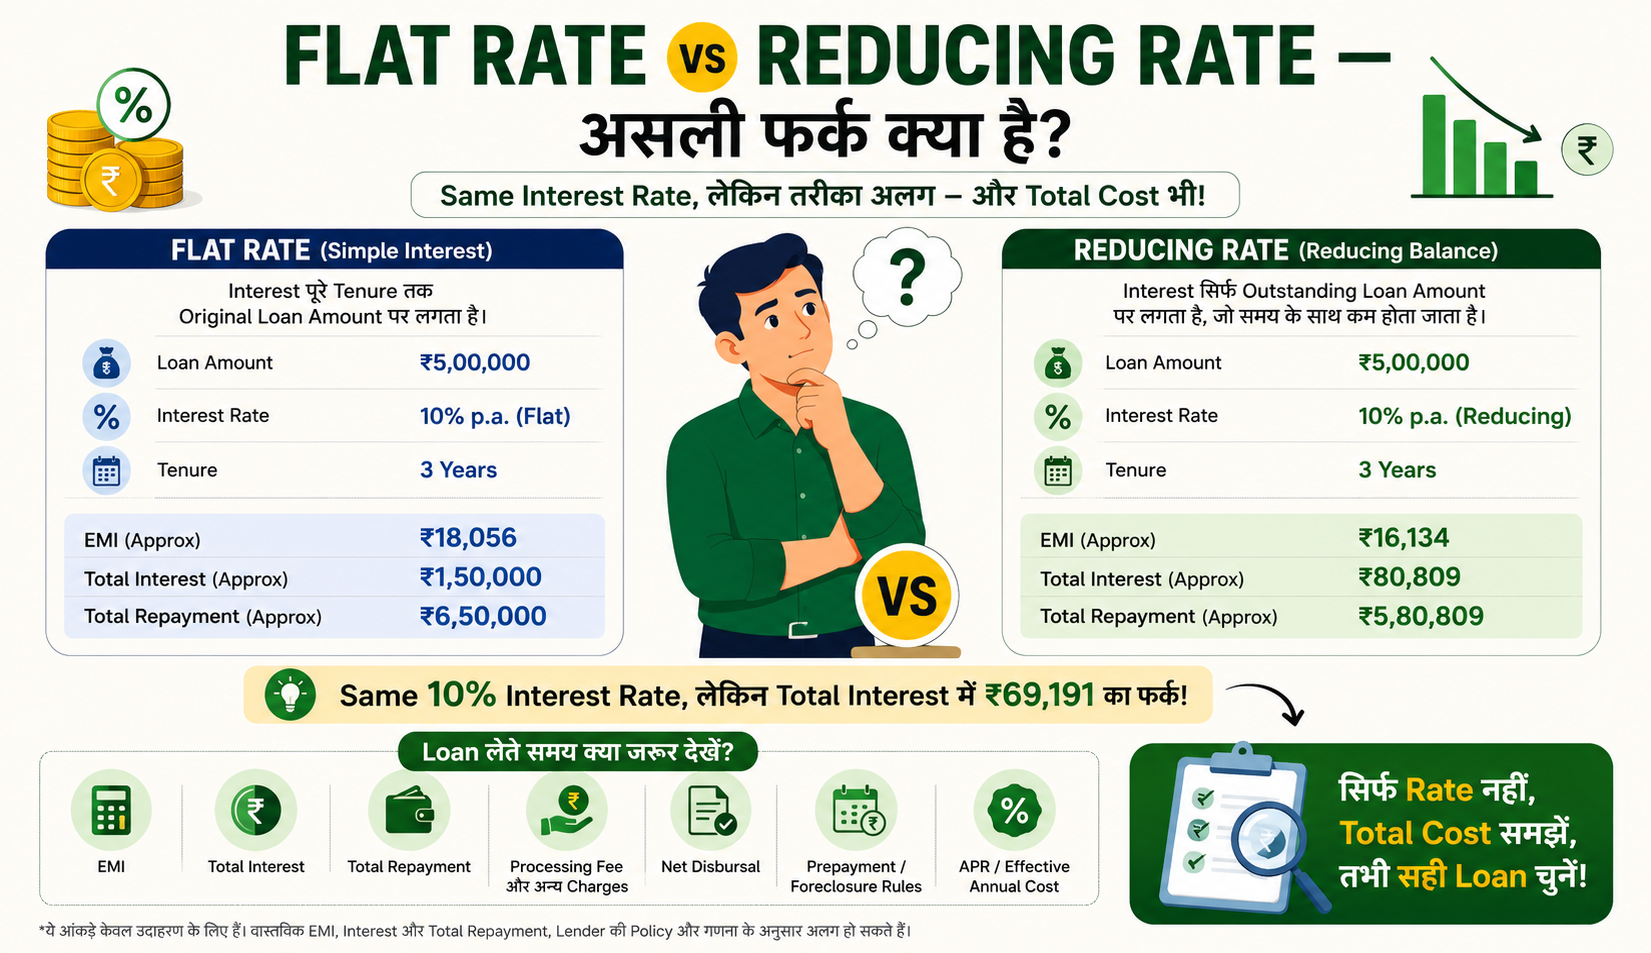
10% Flat और 10% Reducing Rate दिखने में समान लग सकती हैं, लेकिन loan की actual cost अलग हो सकती है। आसान example से EMI, Total Interest और Total Repayment का असली फर्क समझें।

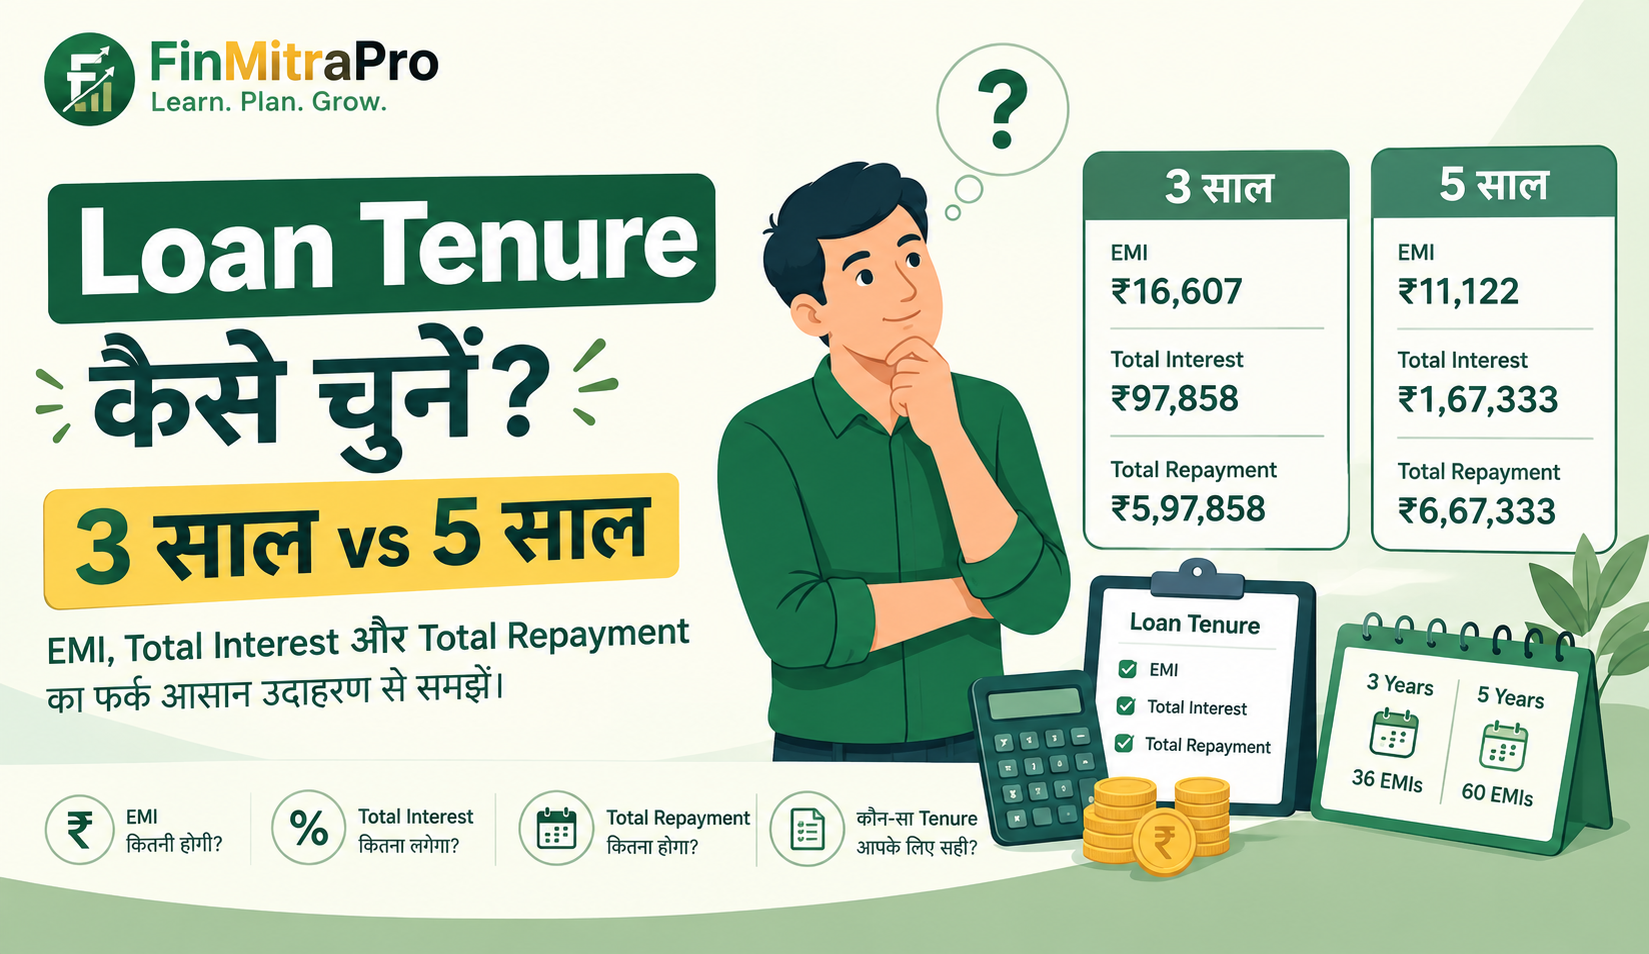
3 साल की Loan Tenure में EMI ज्यादा लेकिन interest कम हो सकता है, जबकि 5 साल में EMI कम लेकिन total cost बढ़ सकती है। आसान example से समझें कि अपने cash flow और total interest के बीच सही balance कैसे देखें।

Loan लेते समय सिर्फ EMI देखना काफी नहीं है। समझिए EMI कैसे बनती है, tenure बदलने से EMI और total interest पर क्या असर पड़ता है, और loan compare करते समय किन numbers को जरूर देखना चाहिए।

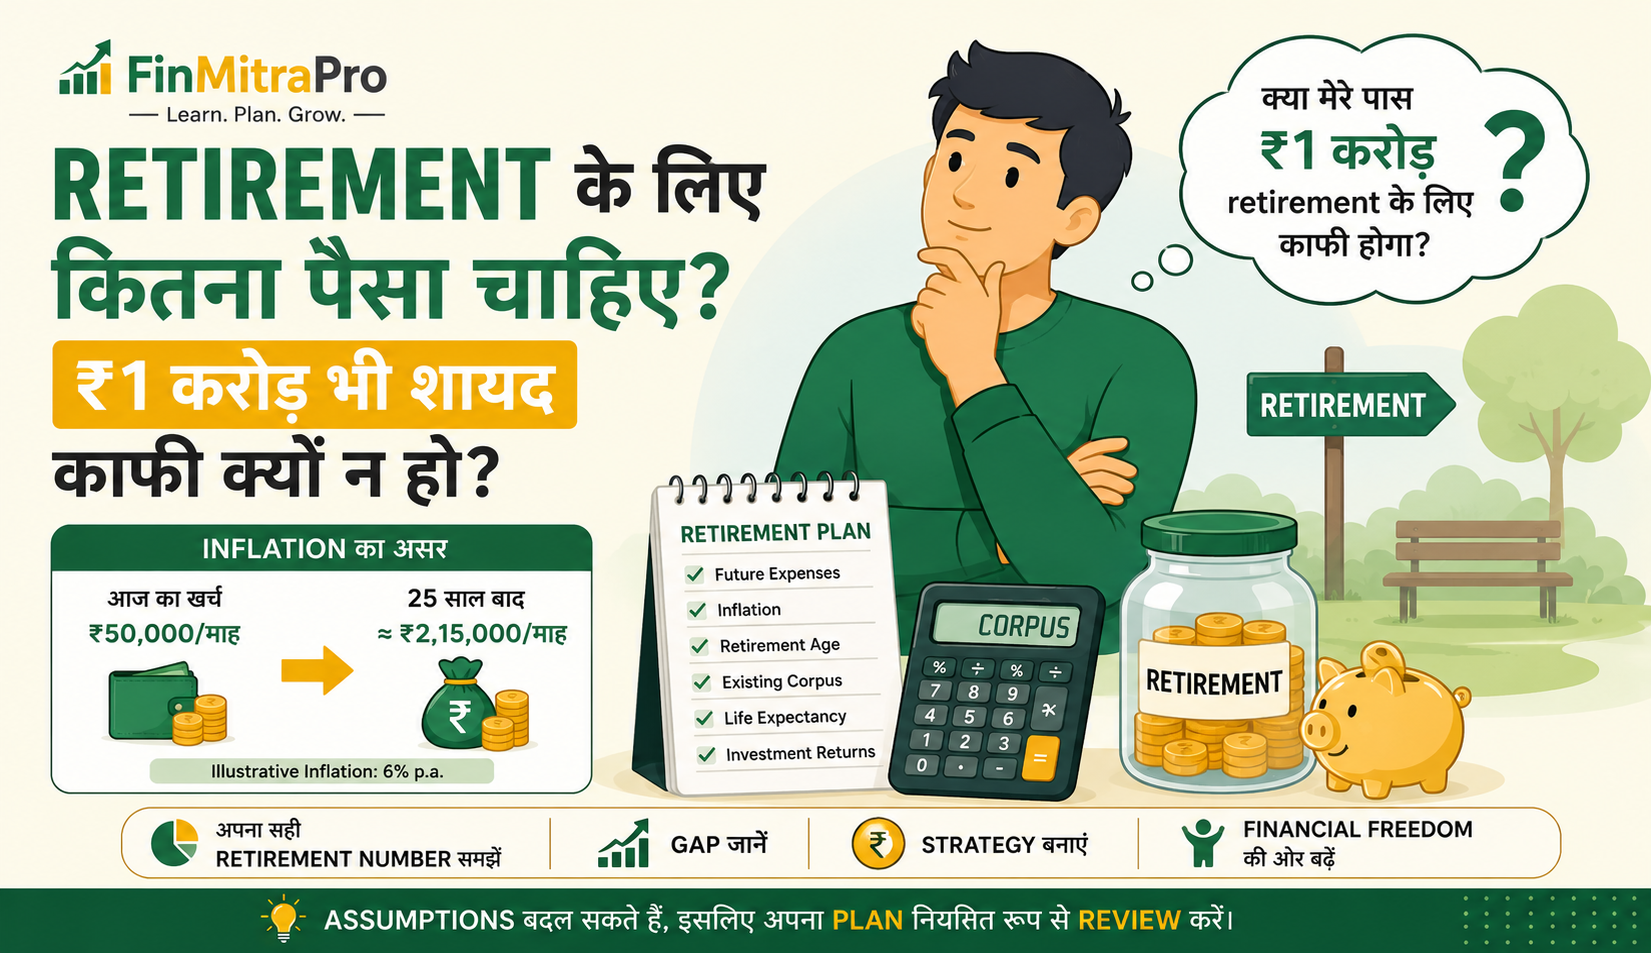
Retirement के लिए ₹1 करोड़ काफी होगा? इसका जवाब आपके expenses, inflation और retirement period पर depend करता है। जानिए अपना estimated Retirement Corpus कैसे समझें।

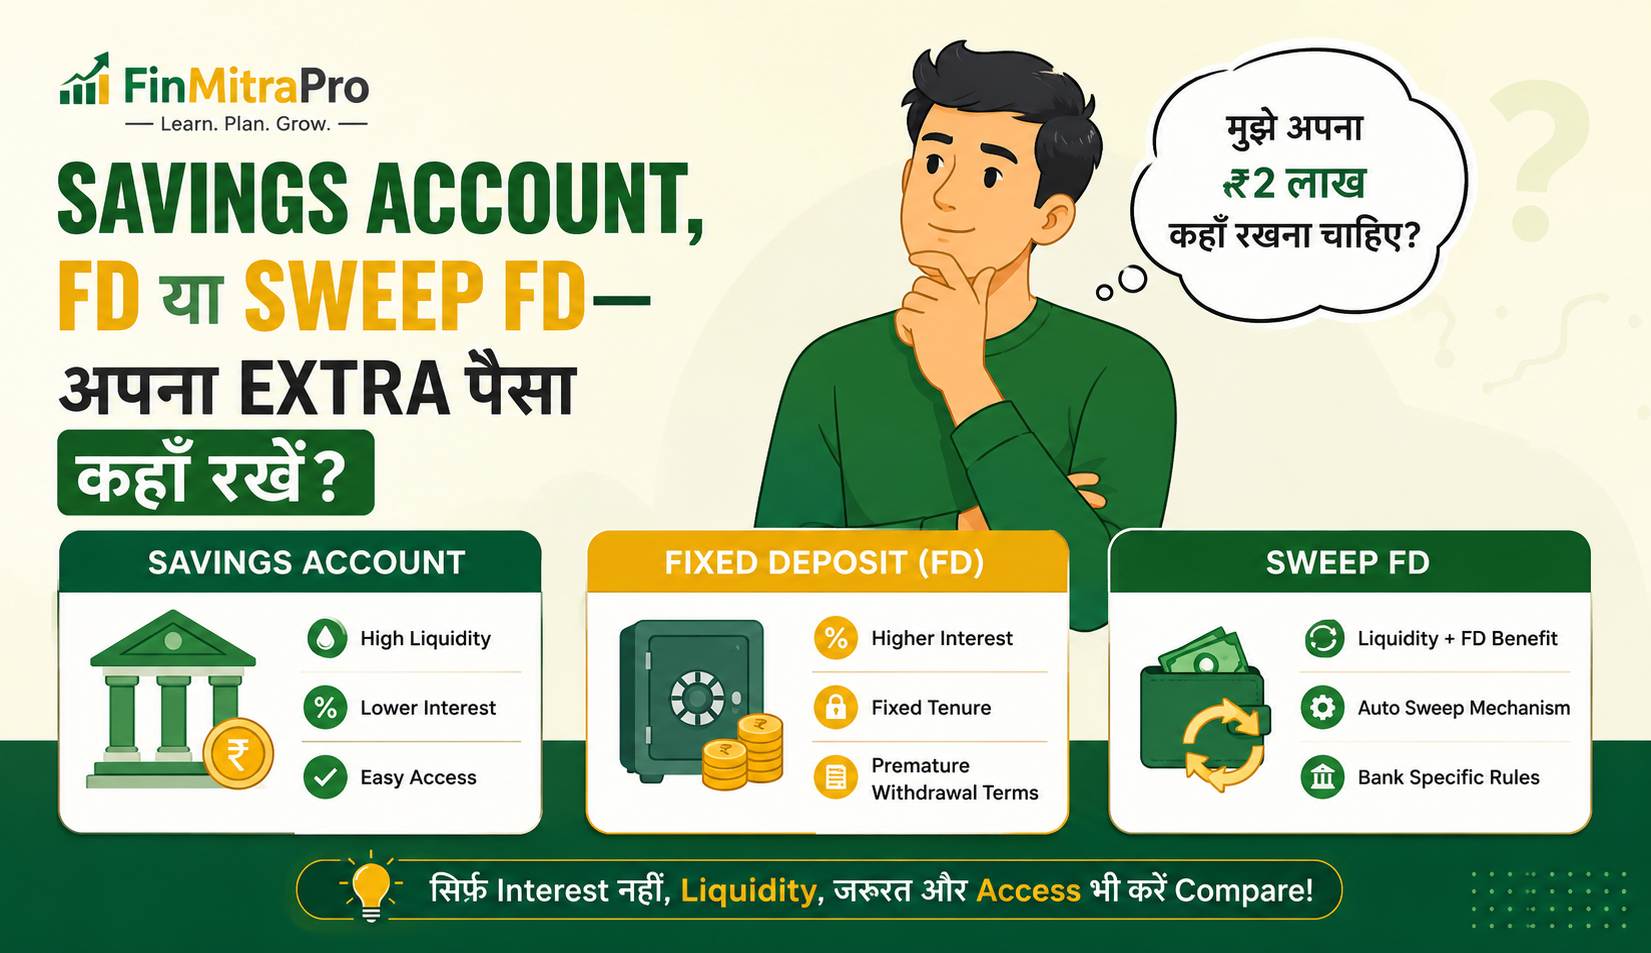
₹1 लाख extra पड़े हैं—Savings Account में छोड़ें, FD करें या Sweep FD use करें? Interest से पहले liquidity, purpose और पैसे की जरूरत कब पड़ेगी, यह समझिए।

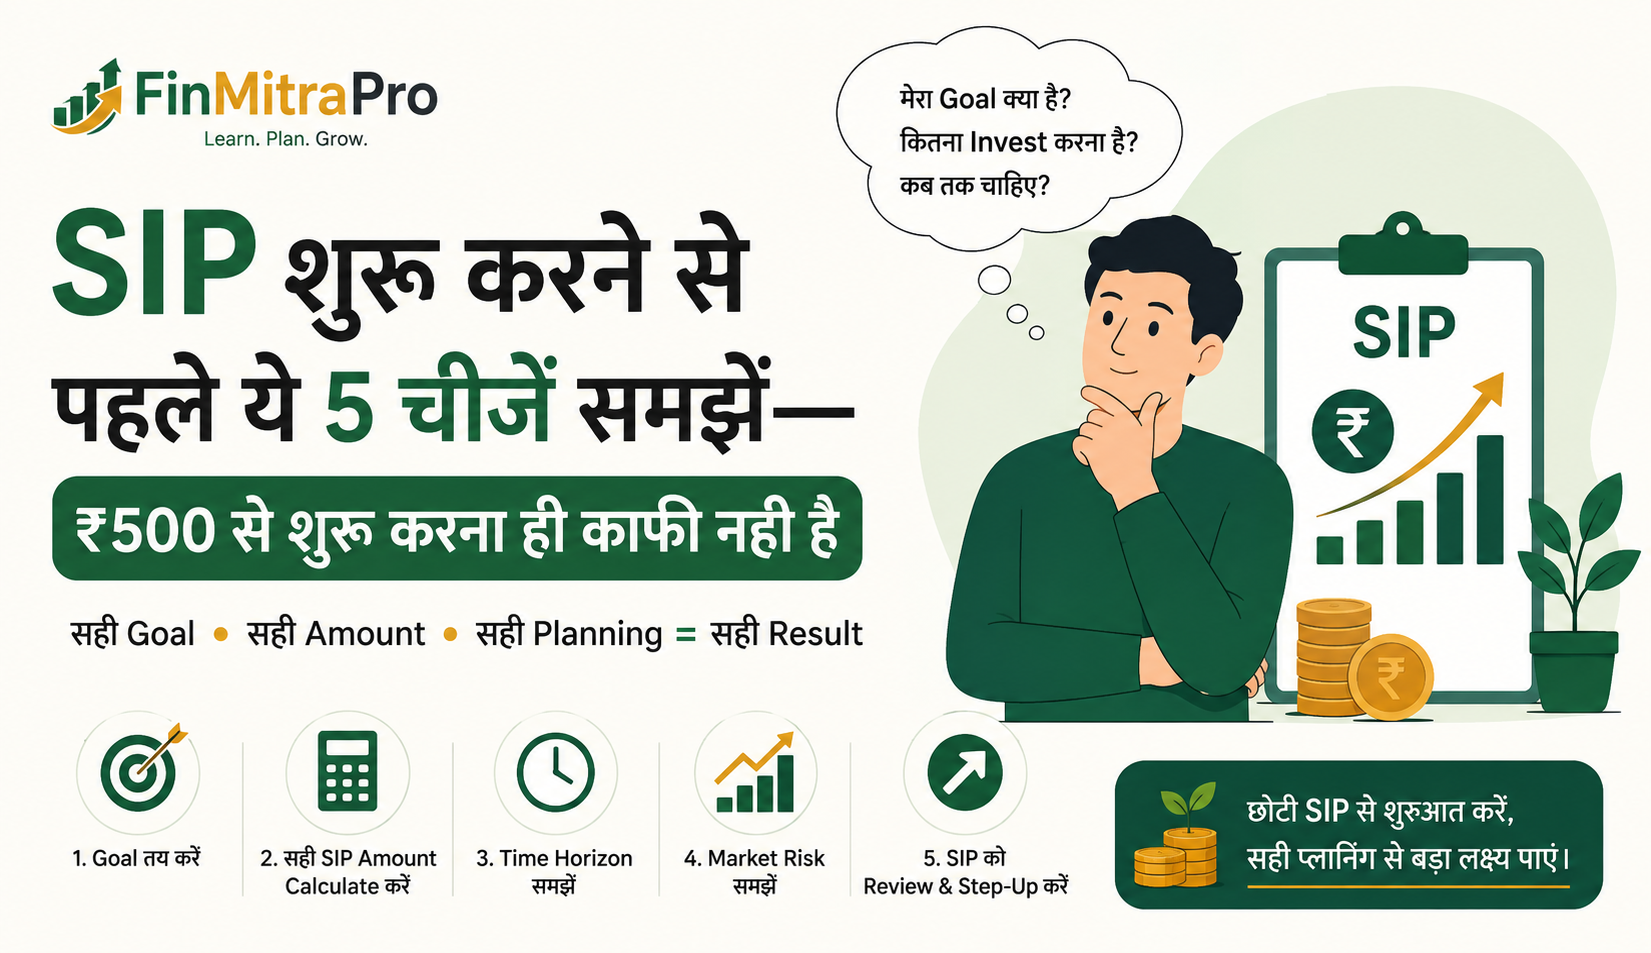
₹500 की SIP शुरू करना आसान है, लेकिन क्या वह आपके Goal के लिए काफी है? SIP शुरू करने से पहले Goal, सही Amount, Time Horizon और Market Risk समझिए।

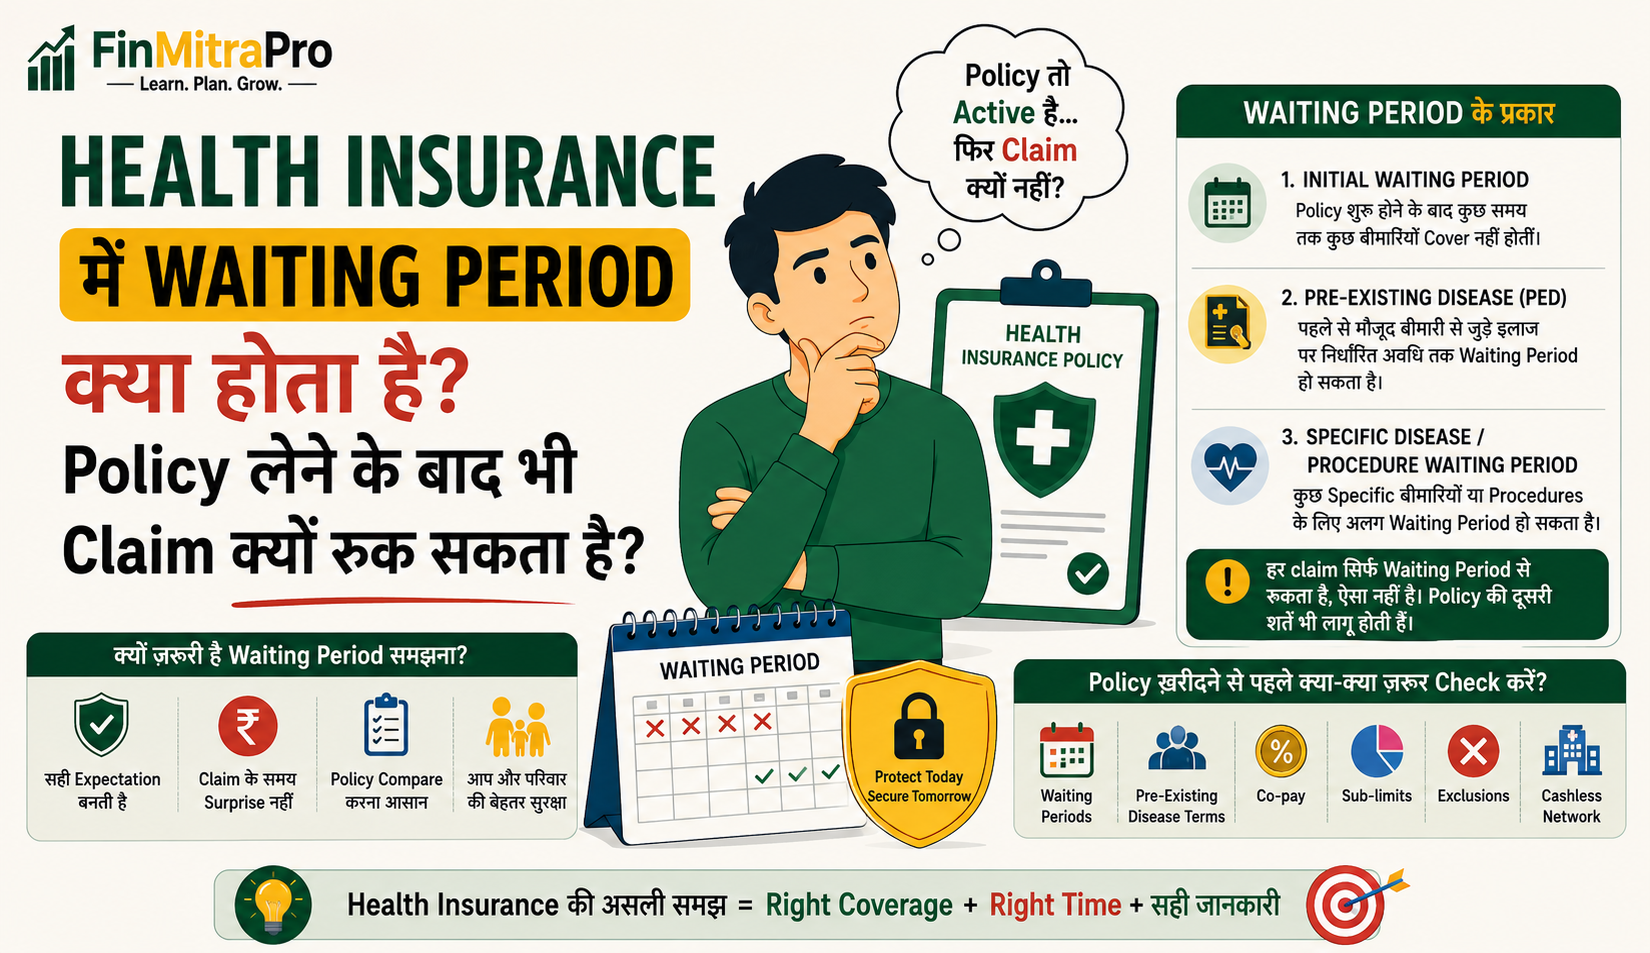
Health Insurance active होने के बाद भी क्या हर treatment तुरंत covered होता है? Waiting Period, PED और specific treatments की conditions आसान examples से समझिए।
सिर्फ पढ़ें नहीं — अपने numbers पर check करें.
Monthly SIP का estimated future value समझें.
Calculate →Future expenses और estimated corpus समझें.
Estimate →Assets − Liabilities से estimated Net Worth देखें.
Check →Minimum Due का estimated cost और time समझें.
Understand Cost →एक topic चुनें, concept समझें, अपने numbers पर test करें और फिर informed financial decision लें.